Capacit’e Infraprojects reported its strongest-ever quarterly execution in Q2 FY27, with revenue reaching a record high despite the challenges typically associated with the monsoon season. The company began the financial year at a slower pace due to labour shortages, but execution improved during the September quarter as workers returned and construction activity picked up across key project sites. Order inflows also remained encouraging, providing visibility for the coming quarters. Although profitability declined slightly, management attributed the dip to specific factors and remains optimistic about sustaining the improved execution momentum in the second half of FY27.
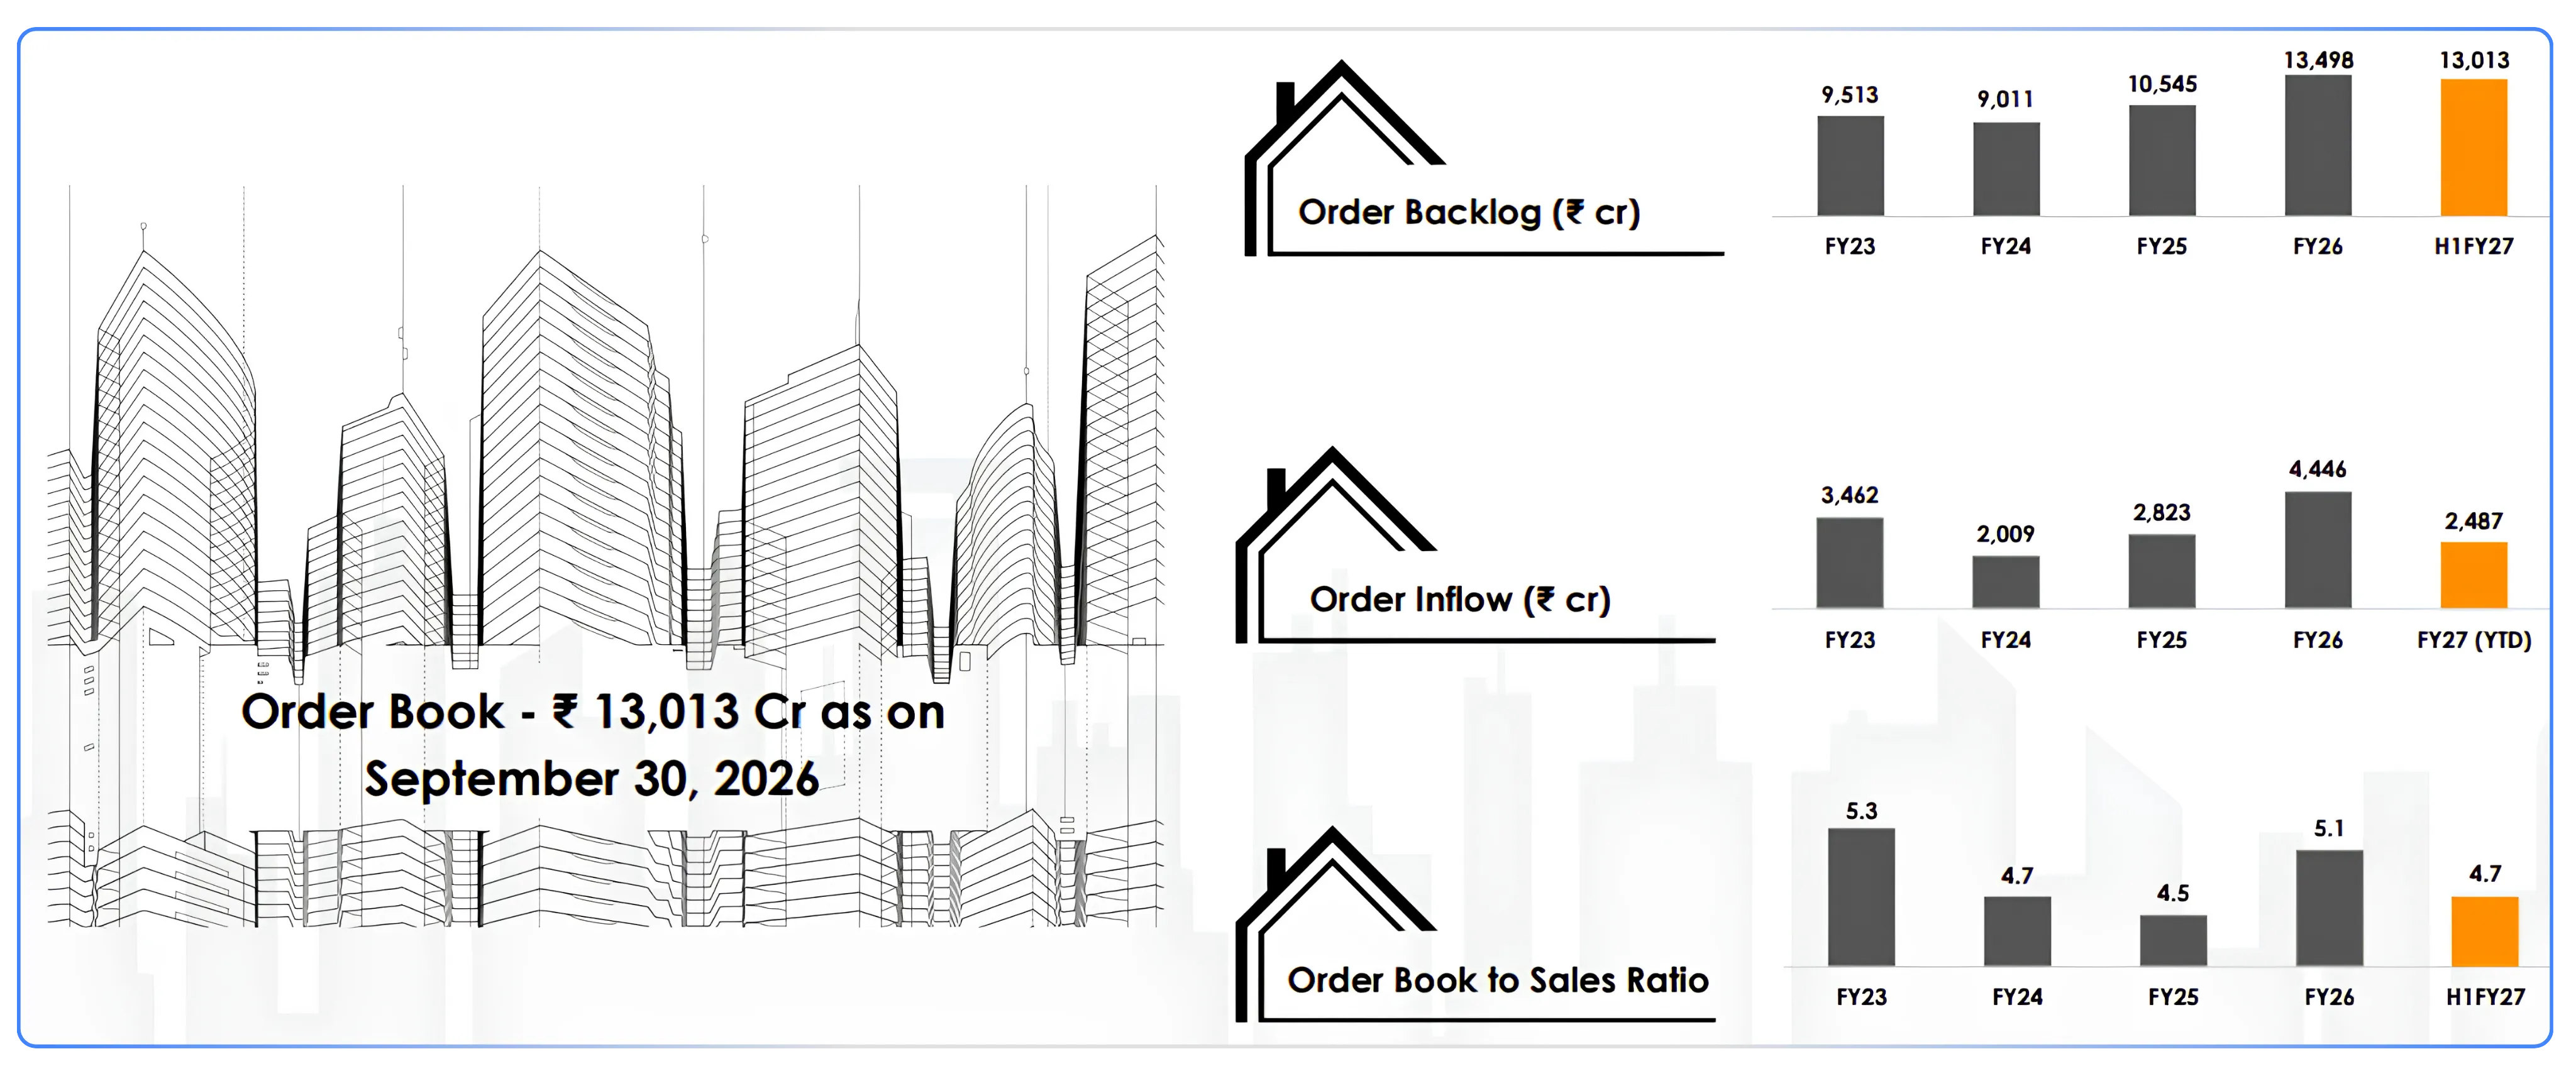
Order inflows have also remained encouraging. Capacit’e has secured new orders worth ₹2,487 crore so far in FY27, including its first project from Mahindra Lifespaces. Another ₹3,270 crore worth of bids are currently under negotiation. The company has set an order inflow target of ₹4,500–5,000 crore for the full year. Management is confident of surpassing this target and indicated that it may revise the guidance upwards in the next quarter.
The company is also taking steps to expand its presence in international markets. On 4 November, its board approved the incorporation of a subsidiary in Dubai, in which Capacit’e will hold a 75% stake. This entity will, in turn, establish a wholly owned subsidiary in Uganda. Both subsidiaries will undertake EPC projects across high-rise and super high-rise residential buildings, commercial complexes, retail developments, healthcare facilities and data centres.
The investments will be made in cash, although the investment amount, subsidiary names and incorporation dates are yet to be finalised. The proposed setup is also subject to the necessary regulatory approvals in the UAE. The company has not announced any overseas order wins so far. However, management expects its international project qualification to improve following the completion of its Maldives project, which is scheduled for this year.
Alongside its international expansion plans, Capacit’e is looking to strengthen its presence in India's tier 2 and tier 3 cities. Construction of buildings will, however, remain its core area of focus.
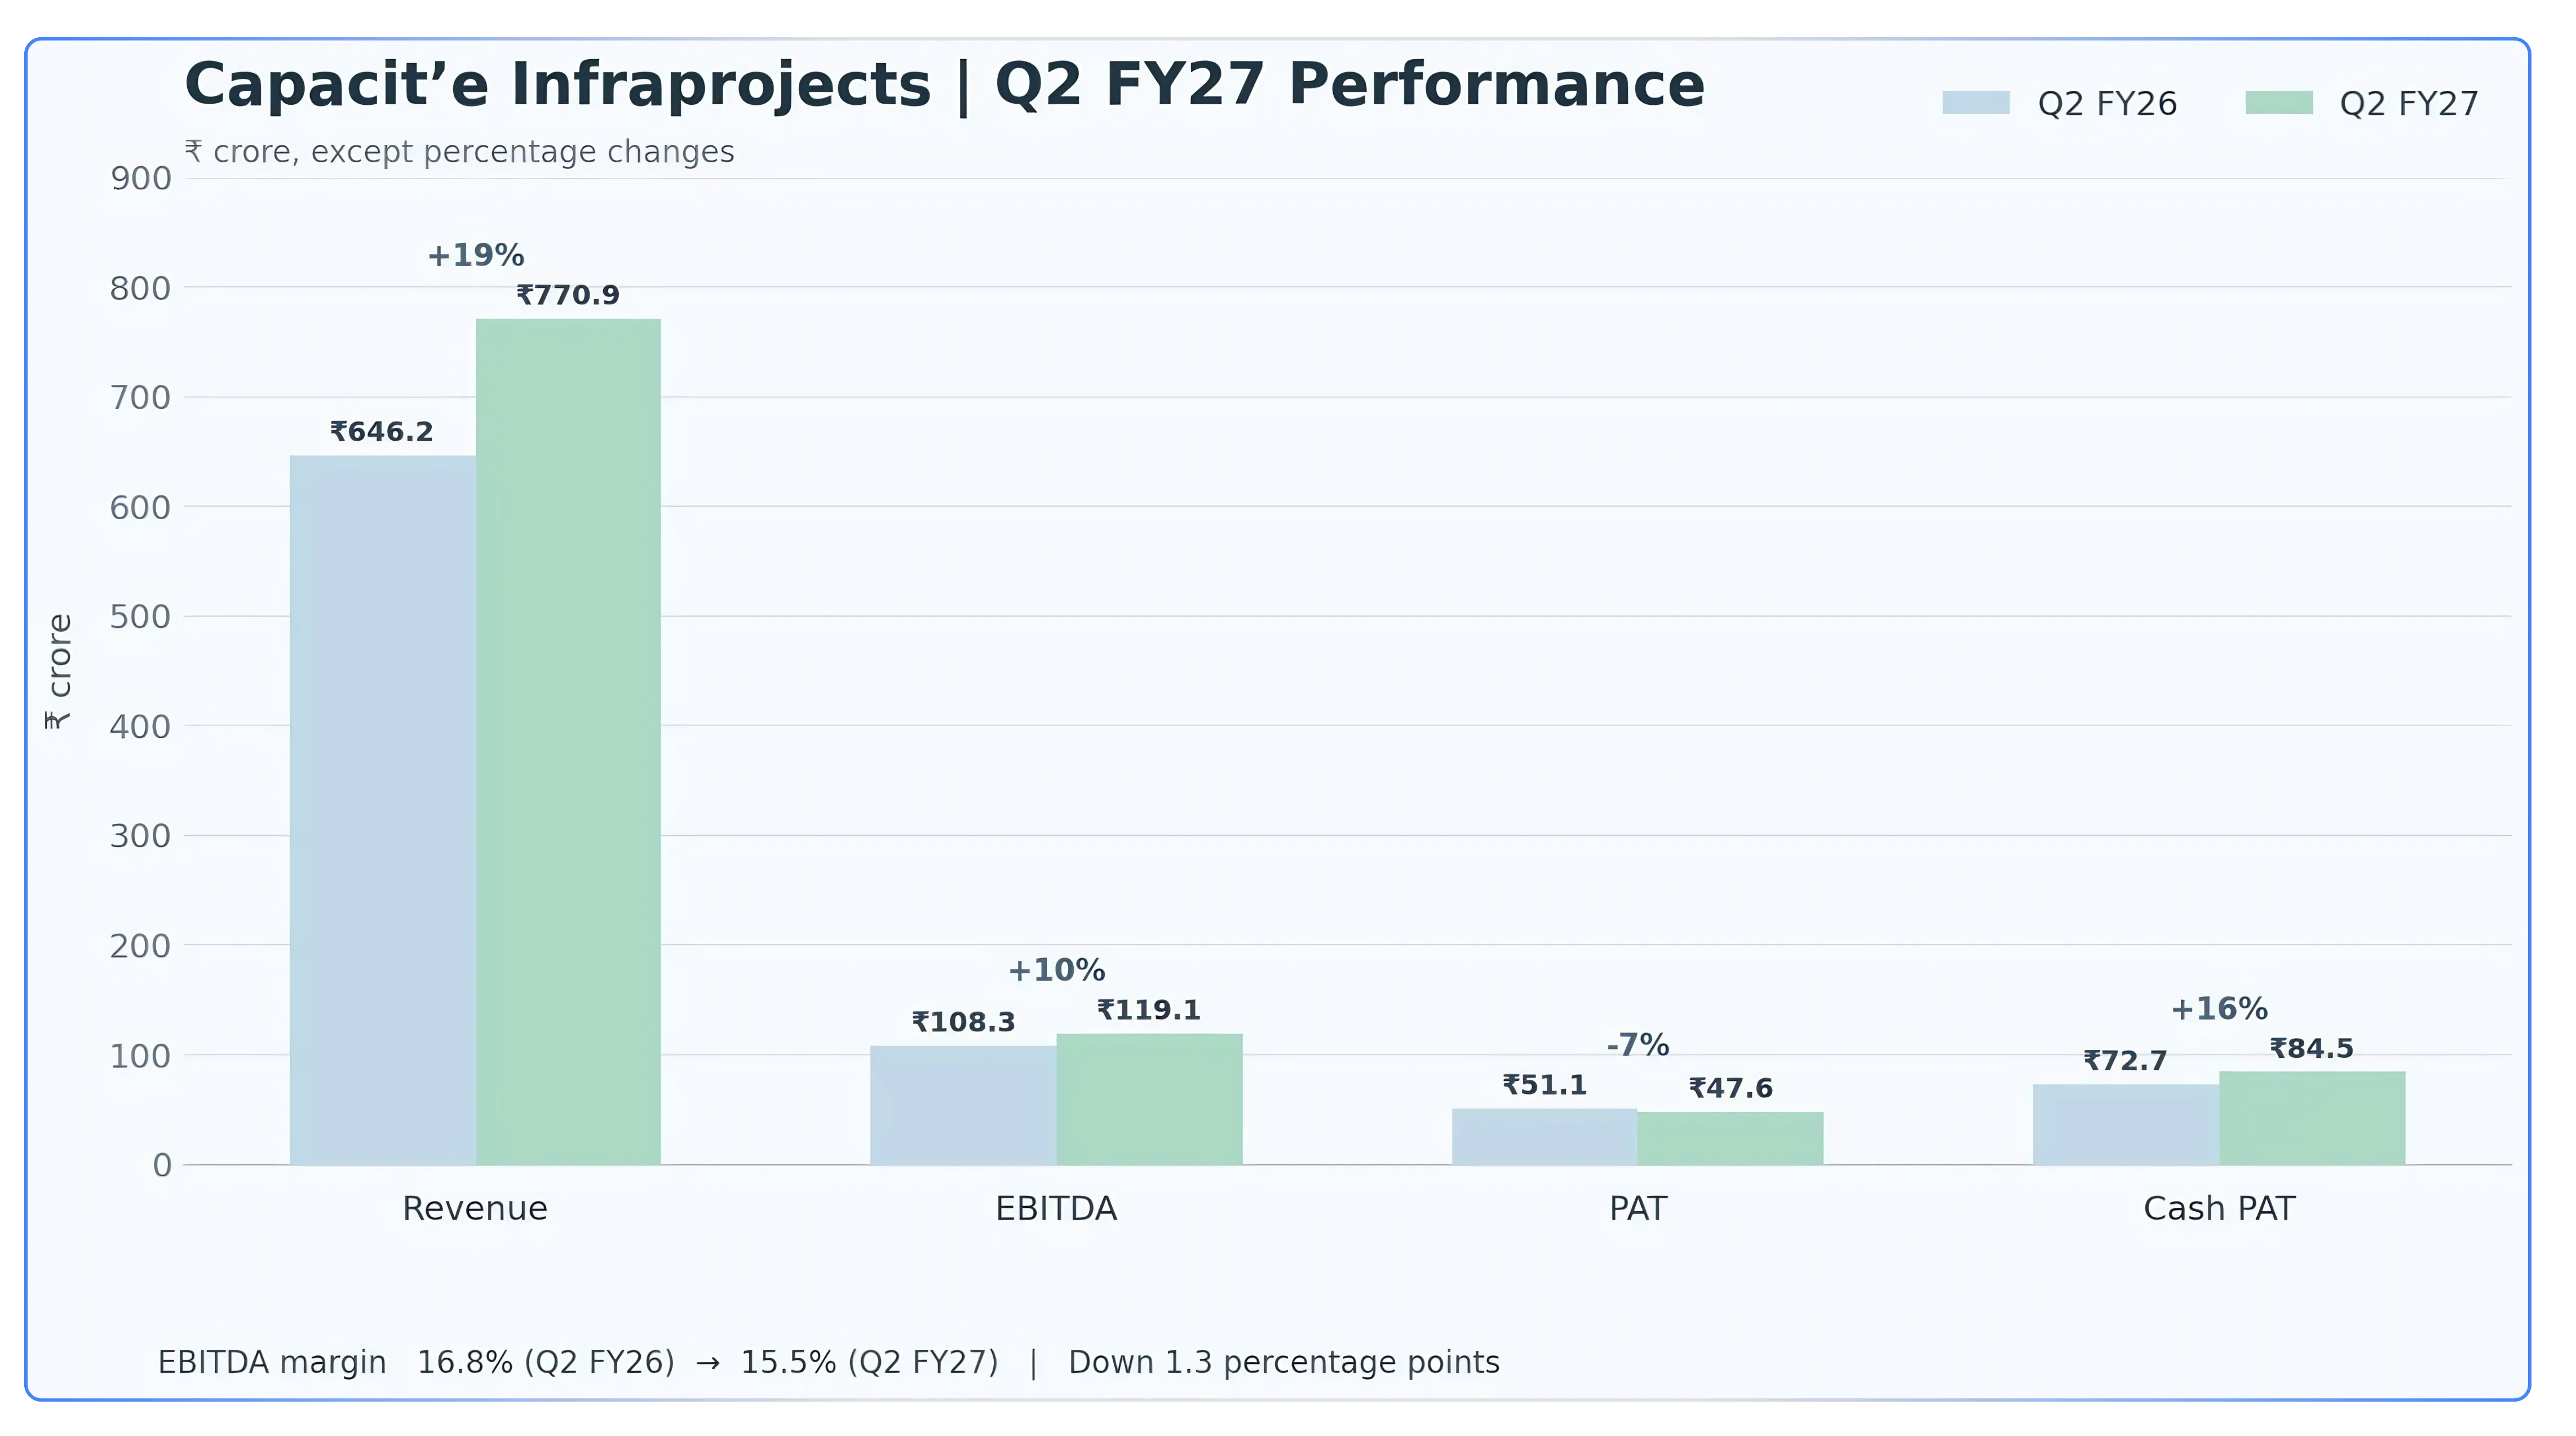
PAT is the profit left after all expenses including depreciation, interest and tax, while Cash PAT adds depreciation back, since it is an accounting charge and not actual cash going out.
For the first half of FY27, revenue grew 13% to ₹1,400 crore, while PAT declined 11% to ₹87 crore.
Three factors weighed on profitability. Steel and electrical costs remained elevated, depreciation increased from ₹24 crore to ₹35 crore following investments in additional aluminium formwork for project sites, and finance costs also moved higher.
The comparison was also affected by a one-time benefit in the corresponding period last year from the sale of non-core assets. This added to the reported decline in profit. However, the underlying performance was better than the headline PAT figure suggests. Cash PAT, which adds back depreciation, grew 16% in the September quarter.
Also Read: A Fundamental Study of Epack Durable Ltd
Where the growth is expected to come from
Management has retained its FY28 revenue target of ₹4,000 crore, compared with ₹2,623 crore in FY26. Achieving this would require a compound annual growth rate of around 23%. Monthly revenue has already crossed ₹260 crore, and the company expects it to exceed ₹300 crore by Q4, translating into quarterly revenue of around ₹900 crore compared with ₹771 crore currently.
Growth is expected to be driven by improving execution across several large projects:
CIDCO: Monthly billing currently stands at around ₹30 crore. Management expects this to increase by 35–40% in Q3 and Q4, with monthly billing reaching at least ₹50 crore next year. This would translate into an annual run rate of ₹600 crore. Additional scope is also expected to be added to the order book this month.
MHADA: Of the 34 rehabilitation towers, 25 have been handed over. Piling work has begun on the sale towers, with management expecting execution to pick up significantly next year. Capacit’e has a 35% share in the project.
NBCC: Monthly billing has crossed ₹60 crore and can reach ₹65–70 crore during months without pollution-related work stoppages in the NCR region. Signature Global: Monthly billing is currently around ₹15 crore and is expected to increase to ₹18–19 crore from Q4.
IIT Bombay: The ₹550 crore project is still at an early stage, with only around ₹70 crore worth of site area handed over so far. The client has indicated that the entire site will be handed over by March 2027. Execution is expected to continue over the following 24 months.
The company's order book stands at ₹13,013 crore, equivalent to approximately 4.7 times its annual revenue. Public-sector projects account for 54% of the order book, while private-sector projects contribute the remaining 46%. Residential construction dominates the portfolio, accounting for 64% of the total order book.
Margins
For FY27, management has guided for an EBITDA margin of 15.5–16.5% and a cash profit margin of around 10.5–11.25%. Over the long term, the company is targeting an EBITDA margin of 16–17%.
Margin pressure is largely due to a time lag in recovering higher input costs on government projects. These projects have price escalation clauses, but the adjustment formulas typically trail actual market prices by six to nine months. Management indicated that this gap was around 5–6% in Q1 and has since narrowed to approximately 2%.
The company did not make any additional provision for commodity price increases in Q2. If input prices stabilise and the escalation formulas catch up with market rates, some of the provisions made earlier could be reversed in Q4, providing support to margins.
The completion of the Maldives project, expected this year, is another positive factor. Management expects its completion to improve the consolidated EBITDA margin in FY28.
Balance sheet
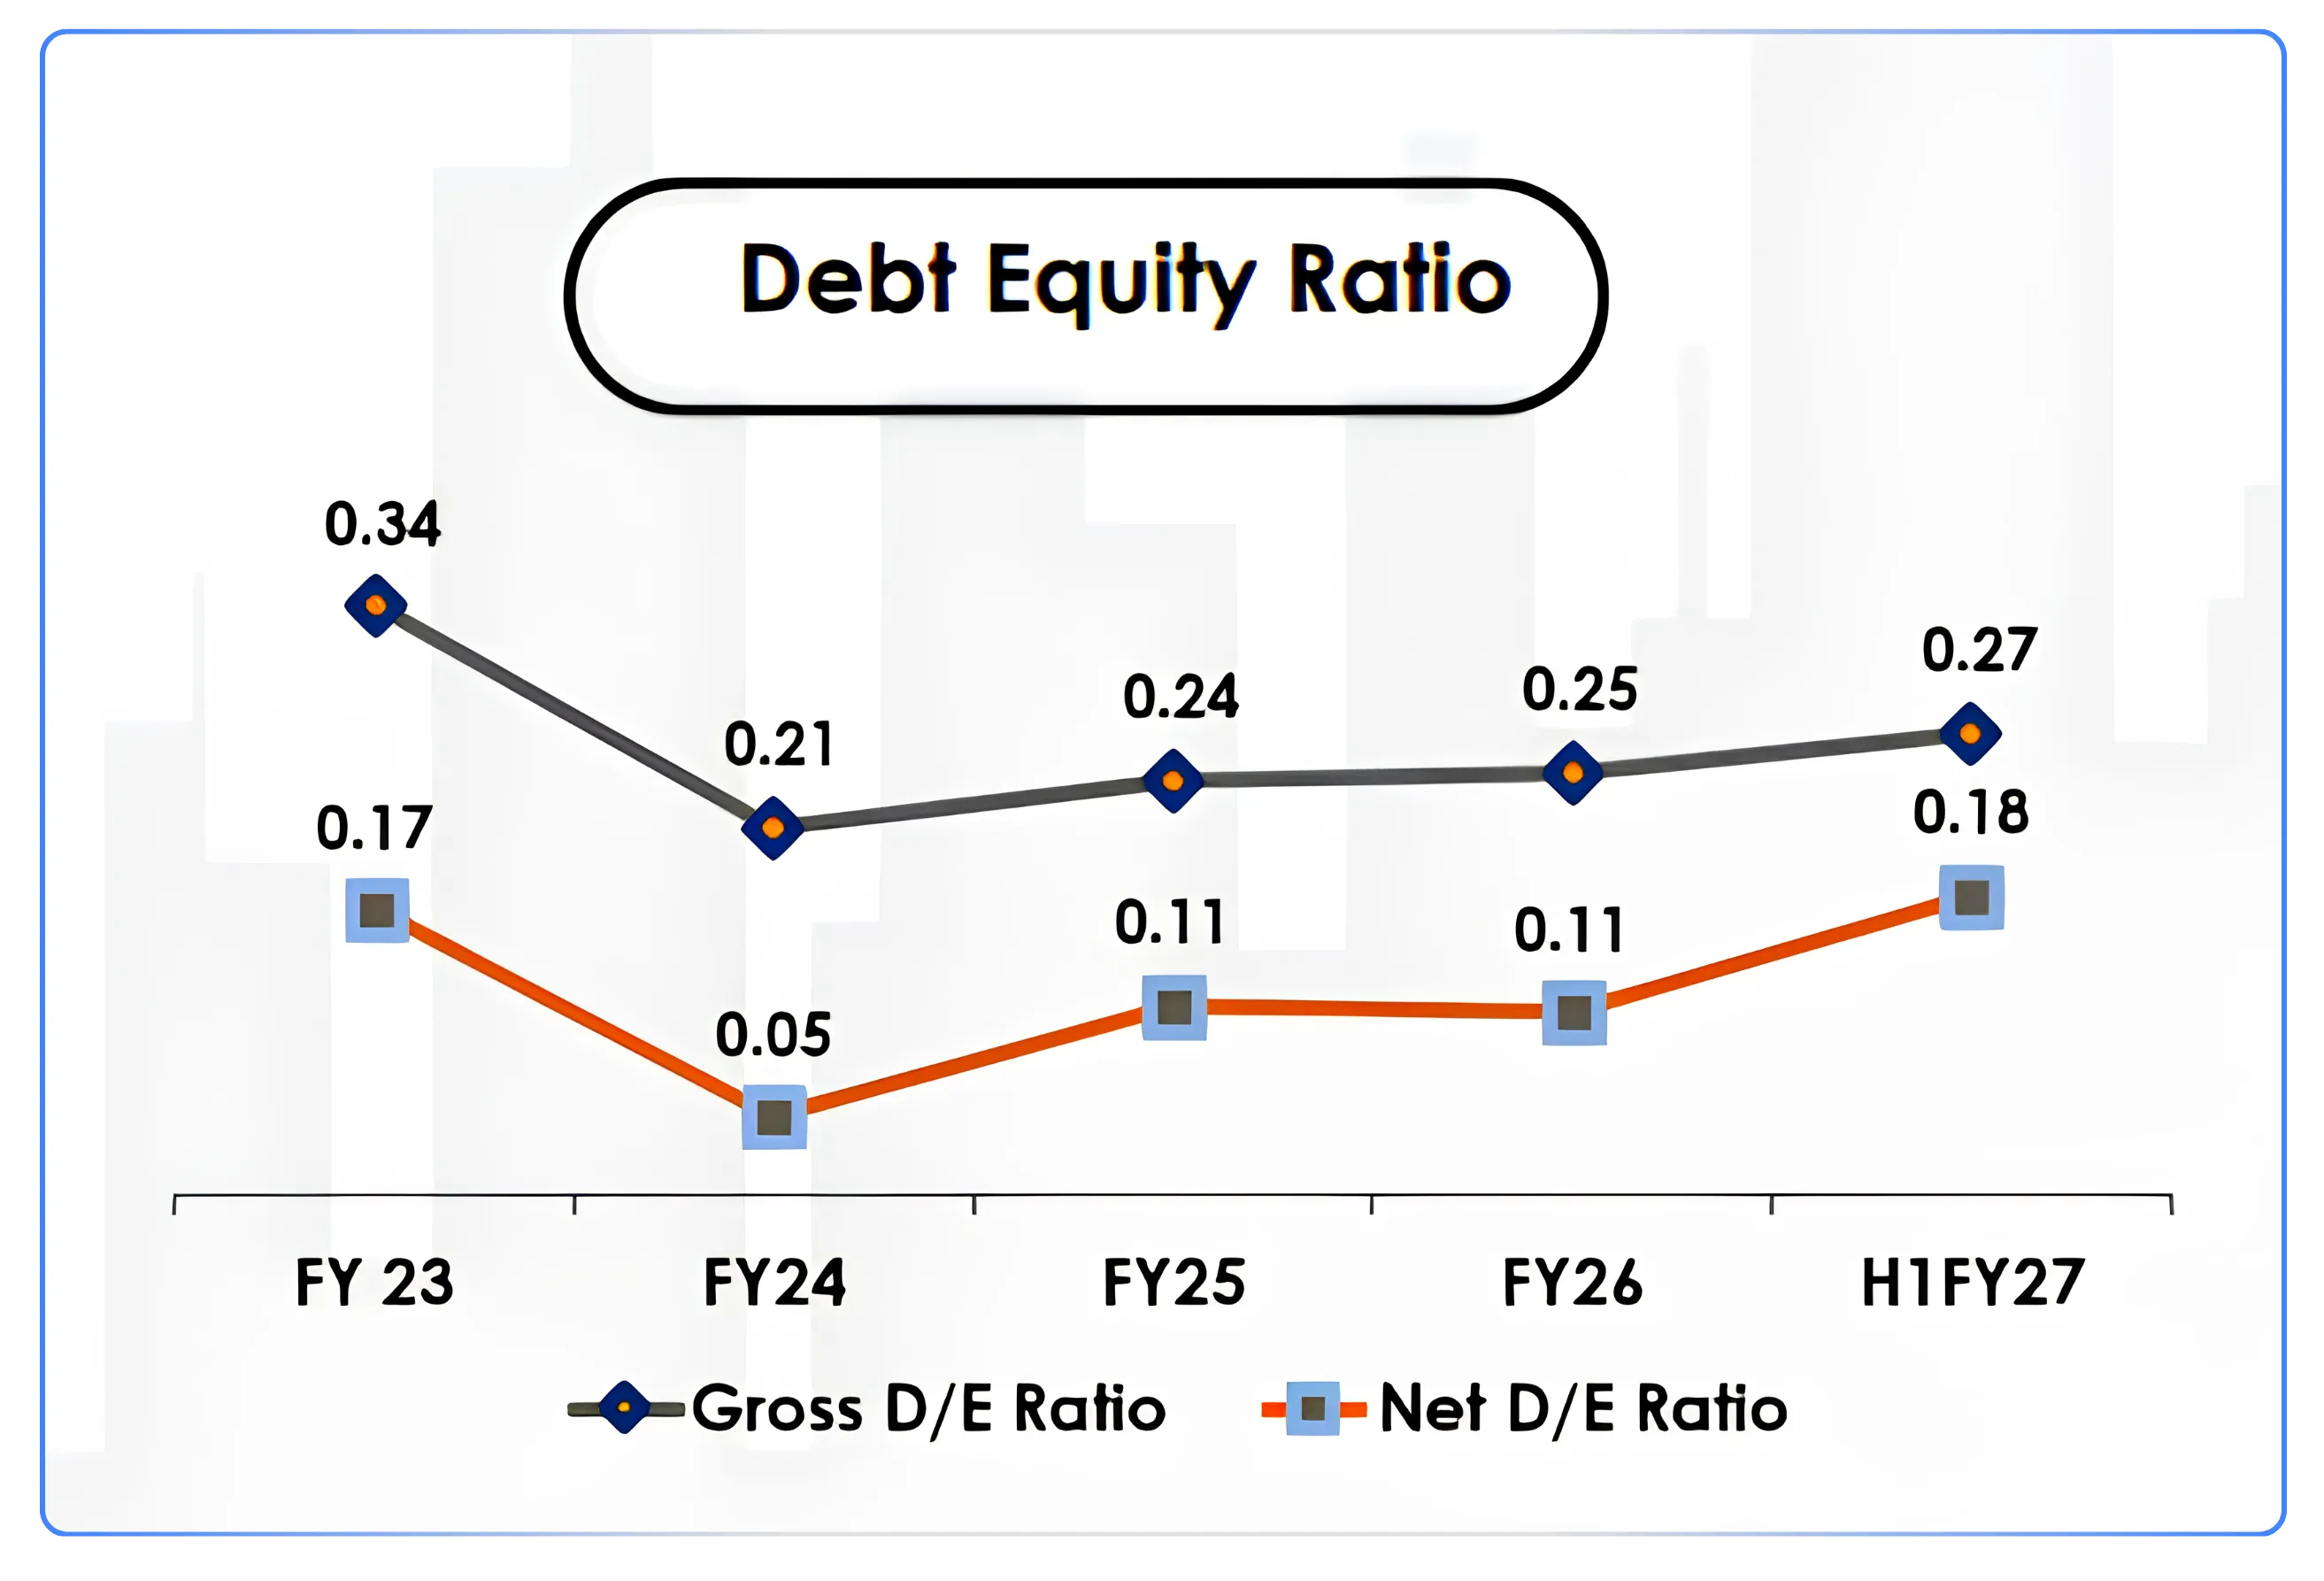
Capacit’e's balance sheet remains comfortable, with gross debt-to-equity at 0.27x. Management expects gross debt to remain broadly flat during FY27, while term loans are being repaid at approximately ₹10 crore per month. Working capital days have improved by 11 days compared with Q1, and management expects this improvement to continue.
The company has also made significant progress in reducing promoter share pledges. The pledged loan limit has been brought down from ₹608 crore to ₹140 crore, with only around 50 lakh shares remaining pledged, entirely against SBI working capital facilities. Management aims to release the remaining pledge by 31 March 2027.
Separately, Capacit’e is monetising non-core properties acquired through settlements following the COVID period. Of the original ₹350 crore worth of assets, approximately ₹200 crore has already been recovered. The company expects to recover another ₹52–54 crore during the current financial year.
The valuation
As of 6 November 2026, Capacit’e has a market capitalisation of ₹1,448 crore and trades at a P/E multiple of 7.9x. For context, the company reported FY26 revenue of ₹2,623 crore and has an order book of ₹13,013 crore.
Its financial growth over the past four years has also been encouraging. Since FY22, revenue has grown at a CAGR of 18%, EBIT at 27% and PAT at 42%. This indicates that profit growth has outpaced revenue growth over the period.
What to keep an eye on
Margins: Whether EBITDA margins improve towards the 16% mark as execution picks up and input cost pressures ease.
Q3 and Q4 execution: The company's target of crossing ₹300 crore in monthly revenue will depend on the timely ramp-up of its major projects.
NCR pollution restrictions: Management has factored in a potential revenue loss of ₹45–50 crore this winter due to pollution-related construction restrictions. The actual impact will be worth tracking.
Cash flow: Net debt increased from ₹204 crore in March to ₹350 crore in September. Improvement in working capital and cash generation will be important to monitor.
Overseas expansion: The proposed Dubai and Uganda subsidiaries are yet to be incorporated. The announcement of the first overseas order and details of the planned investment will help assess the scale and seriousness of the company's international expansion plans.
Disclaimer: The information provided in our blogs is for informational purposes only and should not be construed as financial, investment, or trading advice. Trading and investing in the securities market carries risk. Always conduct your own research and consult with a qualified financial advisor before making any investment decisions. Past performance is not indicative of future results. Copyrighted and original content for your trading and investing needs.
© 2026 — Tradejini. All Rights Reserved.